The terms "financial advisor" and "financial planner" get used interchangeably online, in ads, and even in casual conversation. But they don't always mean the same thing.
Before choosing someone to help manage your money and your future, it helps to understand what actually separates the two roles, along with why a CFP® designation changes the equation. Getting this right matters more heading into retirement, a divorce, or after losing a spouse than it does for a single quick transaction.
Key Takeaways
- A CFP® credential requires standardized education, an exam, verified experience, and a fiduciary commitment that a generic financial advisor title does not require on its own.
- The real difference between a financial advisor and financial planner usually comes down to scope of service, not just semantics.
- Asking the right questions upfront can reveal whether someone is offering a single transaction or a coordinated, long-term plan.
What Does "Financial Advisor" Actually Mean?
"Financial advisor" is a broad term used by professionals who provide different types of financial services. The title alone doesn't tell you how someone is registered or how they are compensated. It also doesn't necessarily tell you what kind of services they provide.
For example, investment advisers and investment adviser representatives are subject to a fiduciary duty when providing investment advice. Other financial professionals may operate under different regulatory frameworks based on their role and the services they provide.
When comparing a financial planner vs. financial advisor, it's worth looking beyond the title. Understanding how someone works and what obligations apply to the relationship can give you a clearer picture of what to expect.
What Is a Financial Planner?
A financial planner typically takes a wider view of someone's financial life. Rather than focusing on a single account or product, planning tends to bring together retirement income, tax strategy, estate planning, and risk management under one coordinated approach.
Fero Financial's own approach to financial planning works this way too, treating each account as part of one strategy where every piece supports the others rather than standing on its own.
That coordinated approach is often the clearest marker separating a financial planner from a financial advisor. A planner is generally thinking several steps ahead, not just about the next transaction.
CFP vs. Financial Advisor: Why the Credential Matters
The CFP® designation is one of the clearest ways to tell the two apart. Earning it requires specific coursework, a comprehensive exam, verified experience, and an ongoing commitment to a fiduciary standard.
CFP vs. financial advisor is a comparison between a professional certification and a broader description of someone who provides financial services. The CFP® mark signifies that a professional has met specific requirements for education, examination, experience, and ethics. Financial advisor, by contrast, describes what someone does rather than a particular credential.
Rebekah J. Fero, CFP®, AIF®, leads Fero Financial's financial planning process, and that credential means her recommendations are built around a client's full financial picture rather than just the products available to sell.
Key Differences Between a Financial Advisor and a Financial Planner
Here is a quick look at how the two titles compare:
- Scope. A financial advisor may focus primarily on investments. A financial planner typically coordinates investments, taxes, estate matters, and insurance together.
- Credentials. A CFP® certification requires specific education, examination, experience, and ethics requirements. Other financial professionals may hold different credentials or registrations based on their role and the services they provide.
- Approach. Advising can be transaction-focused. Planning tends to be ongoing and revisited as life and goals change.
These differences don't mean every advisor falls short. Many are skilled professionals. But a title alone doesn't guarantee a certain scope of service, which is exactly why the difference between a financial advisor and financial planner deserves a closer look before you commit to working with someone.
Why This Distinction Matters When You're Choosing Who to Work With
For someone managing a single investment account, a transaction-focused advisor might be enough. But navigating a major life transition, such as retirement or widowhood, raises the stakes well beyond investment selection alone.
These moments tend to touch taxes, estate documents, insurance coverage, and family decisions all at once. Weighing a financial planner vs. financial advisor becomes less academic and more practical here, since you likely need someone coordinating every piece rather than just managing a portfolio.
This is where the CFP vs. financial advisor question stops being a technicality, since a credentialed planner is trained to look at the full financial picture before recommending next steps.
How Fero Financial Approaches Financial Planning
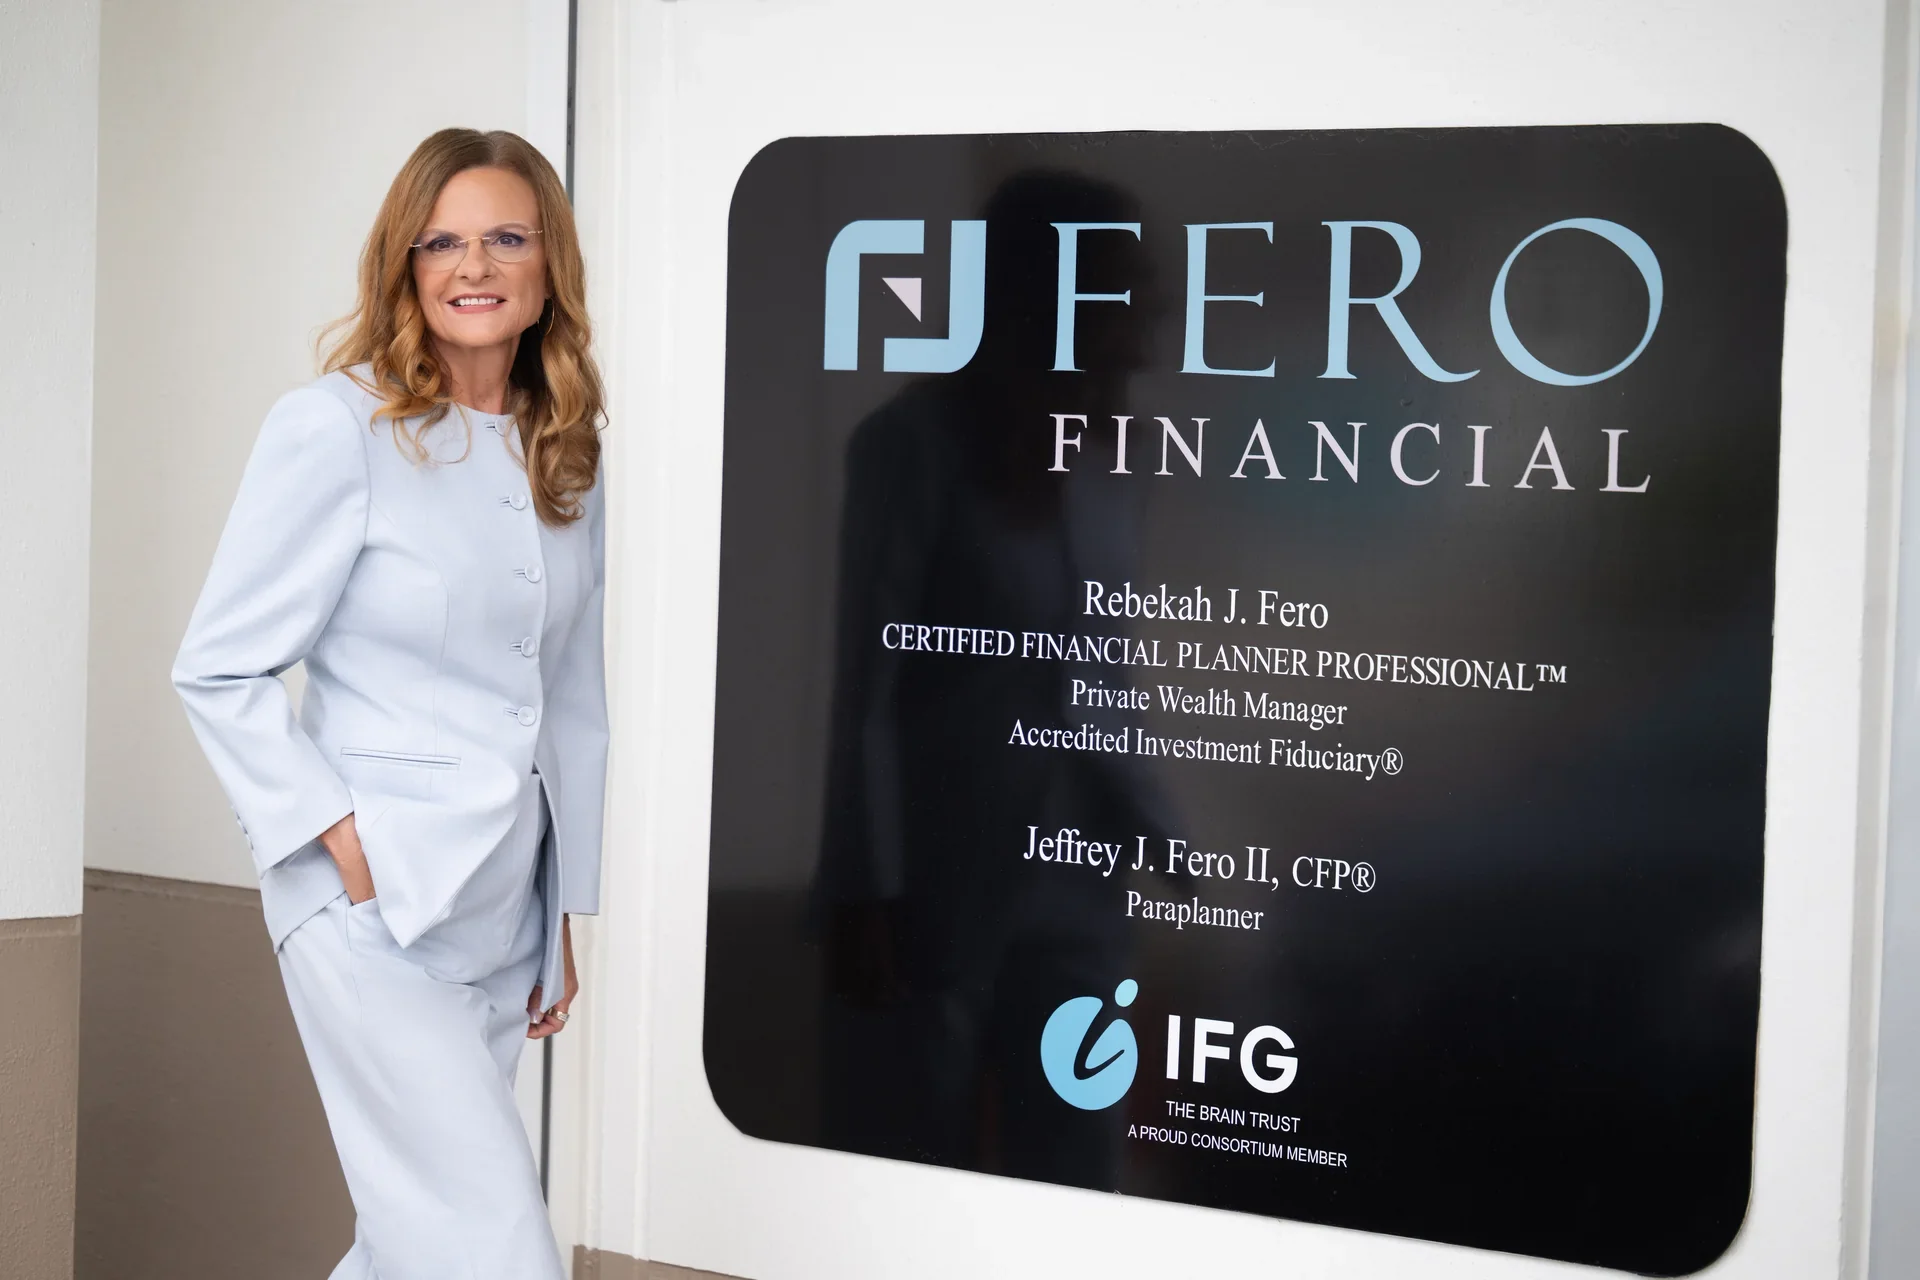
Fero Financial was built around comprehensive planning rather than one-off investment advice. The firm's Intentional Ark philosophy is about organizing what matters most, well before life's unexpected transitions arrive.
As a family-led firm, Fero Financial gives clients direct access to experienced professionals rather than being passed between departments. Rebekah Fero and her team often act as the coordinating point among a client's attorney, CPA, and other trusted professionals so nothing gets handled in isolation.
That kind of coordination, designed to help clients feel informed and organized as decisions come up rather than reacting to them one at a time, captures the difference between a financial advisor and financial planner better than either title does on its own.
Questions to Ask When Choosing a Financial Planner or Advisor
Whether you're weighing a financial planner vs financial advisor or trying to sort out the CFP vs financial advisor distinction on your own, a few direct questions can clarify things quickly:
- Are you required to act as a fiduciary at all times, or only in certain situations?
- Do you hold a CFP® or similar credential, and what did earning it require?
- Will you coordinate with my CPA, attorney, or other professionals, or only manage my investments?
- How is your compensation structured?
- Do you build an ongoing plan, or primarily execute individual transactions?
The answers reveal more about scope and approach than a job title ever will.
Understanding the difference between a financial advisor and financial planner won't make a major financial decision less significant, but it does make it easier to ask better questions. Whoever you choose to work with, clarity about their role, credentials, and approach is worth pursuing before you sign anything.