"Do I need a financial planner?" is rarely a question people ask out of idle curiosity. It usually comes up because something specific already changed, like a new account to track or a decision that suddenly feels bigger than the ones before it.
This guide walks through when the answer to that question tends to be yes, and what actually changes once someone else is coordinating the plan.
Key Takeaways
- The need for a financial planner usually shows up gradually, through growing complexity, rather than one dramatic moment.
- Common reasons for putting it off, like not having enough money or not being complicated enough, don't hold up as well as they sound.
- The real benefit of a financial planner is coordination and understanding, not necessarily better investment performance.
- Whether a financial planner is worth it usually depends on your complexity and your time, not the size of your accounts.
- Fero Financial's CFP®-led, family-run approach is one example of what that coordination can look like in practice.
The Moment This Question Usually Comes Up
Nobody wakes up and decides to hire a financial planner for no reason. Usually, something specific triggers the question, like a retirement date approaching without a clear income plan or a major life transition such as divorce.
Sometimes it's quieter than that. You might simply notice that you're guessing at decisions instead of making them with any real confidence. That quiet uncertainty is often the clearest sign that you need a financial planner, even without a single dramatic event behind it.
The Reasons People Talk Themselves Out of It
Before getting into what a financial planner actually does, it's worth naming the reasons people avoid finding out if they need one in the first place.
"My finances aren't complicated enough yet." Complexity tends to creep in gradually. A few extra accounts or a small inheritance can add up before anyone notices.
"I don't have enough money to justify a planner." This assumes planning is about account size, when it's usually about how many moving pieces need to work together. Coordination, not net worth, tends to determine whether you need a financial planner.
"I can handle this myself." That's true for plenty of people, and self-directed isn't the same as unguided. It's worth being honest about which one actually describes your situation right now.
"I'll deal with this later." Later often shows up as a crisis rather than a calendar reminder. Waiting rarely feels like a strategy in hindsight.
Each of these holds up right until it doesn't, which is exactly why they're worth questioning early rather than after the fact.
What Actually Changes When Someone Else Is Coordinating It
The clearest benefit of a financial planner isn't a better return. It's what happens when retirement income, tax strategy, estate planning, and insurance stop living in separate folders and start working as one coordinated plan.
At Fero Financial, that coordination looks like the financial planning process, pulling every account and decision into a single strategy rather than treating each one in isolation. Fewer things fall through the cracks when someone is actively watching how the pieces fit together.
There's also an educational benefit worth mentioning: instead of just being told what to do, clients tend to understand why a recommendation makes sense for their situation, which makes the next decision easier too.
Weighing the Cost: Is a Financial Planner Worth It
Cost is usually the real question hiding behind whether a financial planner is worth it, and fee structures vary by firm and by service enough that it's worth asking directly rather than assuming.
Whether it's worth it tends to depend less on portfolio size and more on two things: how complex your situation actually is, and how much time and confidence you have to manage it well on your own. Someone with one simple account may not need ongoing coordination, while someone juggling retirement income, an inheritance, and aging parents usually does.
That earlier worry about not having enough money to justify it is really a value question in disguise. The right comparison isn't the fee against your account balance; it's the fee against the time and effort a coordinated plan can help you save.
What This Looks Like at Fero Financial
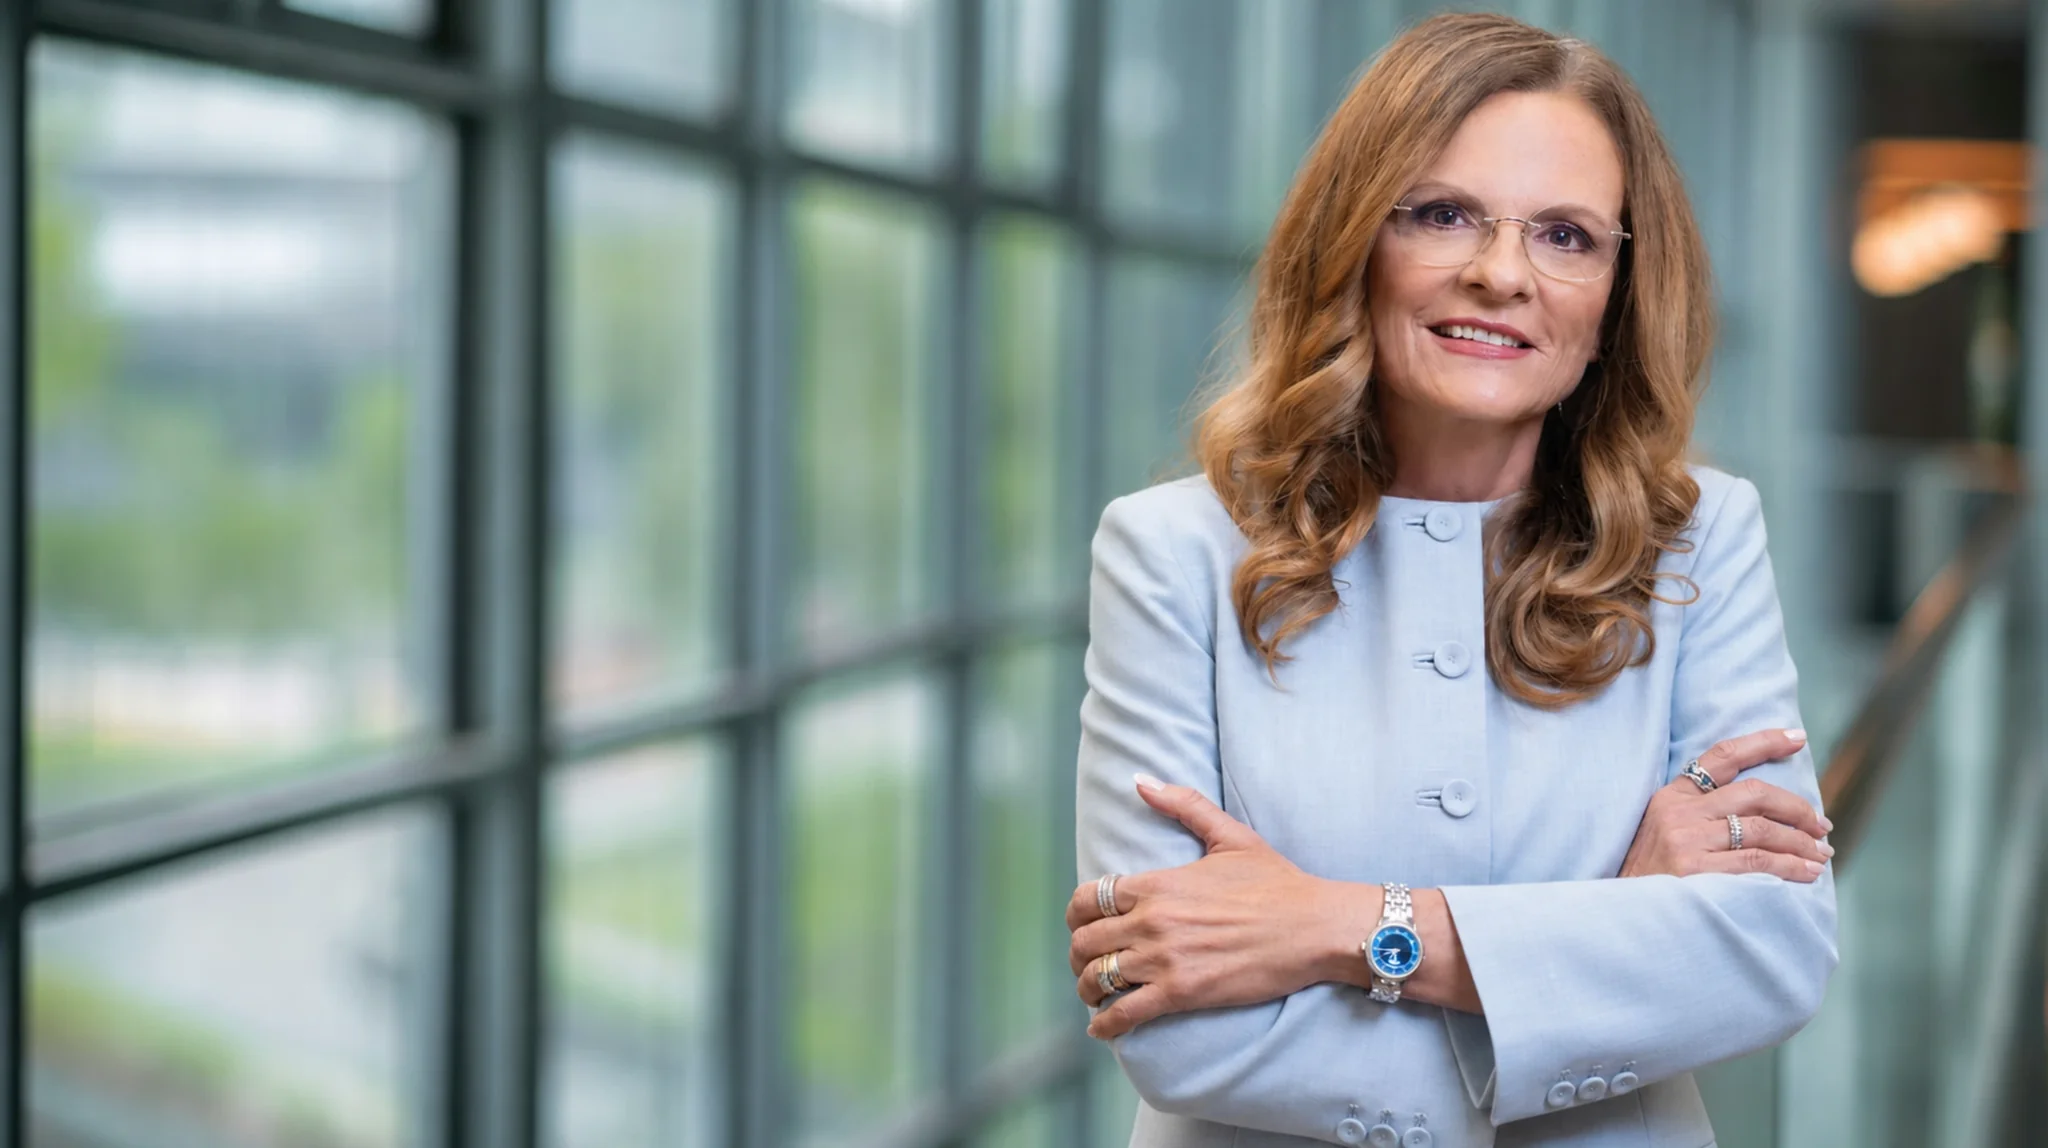
Fero Financial is led by Rebekah J. Fero, CFP®, AIF®, and structured as a family-run firm rather than a large corporate one. That means fewer handoffs and more direct access to the person actually building your plan.
The firm also works to coordinate with a client's other professionals, such as an attorney or CPA, so decisions get made with the full picture in view. This kind of coordination often matters most during a life transition like retirement, widowhood, divorce, or inheritance, where several parts of a financial life shift at once.
A Few Questions Worth Asking First
Whether you're considering Fero Financial or comparing several firms, a few direct questions can clarify things quickly:
- What's included in your planning process, beyond investment management?
- How are you compensated, and what does that look like for someone in my situation?
- Do you coordinate with my other professionals, like my CPA or attorney?
- How often will we revisit the plan as my life changes?
- What happens if my situation gets more complicated than it is today?
The answers tend to reveal more than a firm's marketing ever will.
There's no universal answer to whether you need a financial planner. But if you've been putting off the question because your finances "aren't complicated enough" or you'll "deal with it later," it's worth taking an honest look at whether that's still true.